How to Find the Best Mutual Fund Distributor in India

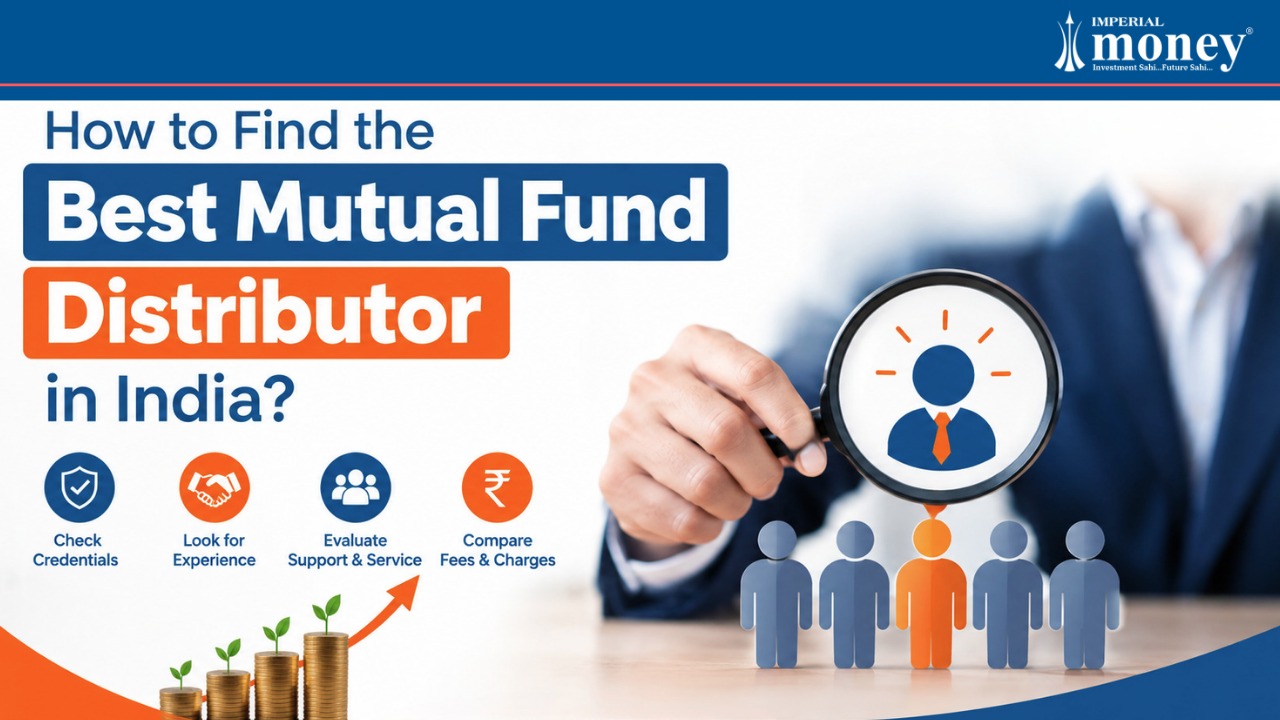
How to Find the Best Mutual Fund Distributor in India banner with selection criteria icons and Imperial Money logo

When you decide to step into the world of investing, choosing the right financial partner is one of the most critical decisions you will make. With countless mutual fund distributors competing for your attention, it is easy to default to picking someone based solely on surface-level service quotes. However, when investing in long-term products like mutual funds and stocks, several deeper criteria are far more vital to your success.

1. Look Beyond Initial Service Quotes

While initial service quality and smooth onboarding matter, settling with a distributor purely based on an initial quote can lead to unpleasant surprises later. Once a firm comprehensively assesses your personal and family financial details, final advisory structures or service parameters may shift. Always evaluate the long-term value rather than superficial upfront offers.

2. Prioritize Financial Stability

Purchasing funds and building a portfolio means entering into a long-term contractual relationship. You need to partner with an established firm capable of weathering economic cycles and market volatility. Stability ensures your advisor remains operational and steady through every market downturn.

3.Assess Market Dynamics and Expert Adaptation

Market conditions dictate the right investment avenues at any given time. A premier mutual fund distributor doesn’t just push static products; they adapt your asset allocation based on prevailing macroeconomic trends, ensuring your capital is positioned defensively or aggressively when required.

4. Evaluate Transparency and Compliance

Always ensure your mutual fund distributor is AMFI-registered and operates with complete transparency. Clear disclosures regarding structures, zero hidden fees, and adherence to regulatory standards protect your investments and build long-term trust.

Conclusion

Finding the best mutual fund distributor in India—such as an established expert right here in Nagpur like Imperial Money—requires looking at financial stability, transparency, and research-driven guidance. Make an informed choice to secure your financial future.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
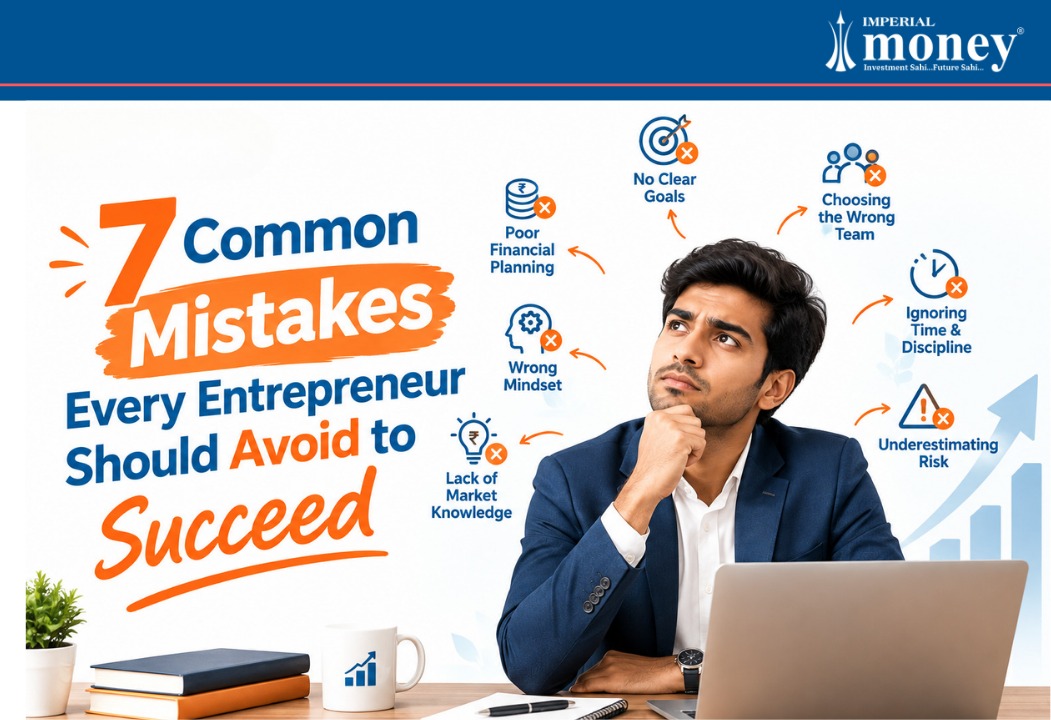
7 Common Mistakes Every Entrepreneur Should Avoid for Success

The history of business dates back to 3000 BC when humans first realized the need to trade resources and satisfy mutual necessities. Since then, the business world has evolved dramatically. While modern entrepreneurs and organizations have formulated countless strategies to succeed, the fundamental rules keep shifting based on market needs and consumer acceptance. Even visionary companies and legendary figures—from Nokia, Kodak, and Compaq to PepsiCo’s near-bankruptcy and Amitabh Bachchan’s historic revival with ABCL—have faced monumental hurdles.

Download the Imperial Money Mutual Fund App to build long-term financial security alongside your business ventures.

1. Defining Market and Customers Incorrectly

The most basic mistake an organization can make is failing to identify its true target audience. No matter how brilliant your plan or efficient your team, it will fail if it lacks direction. Furthermore, many startups overlook proper marketing budgets to cut costs, relying solely on free channels and losing the chance to reach the right buyers

2. Assuming Monopoly and Overconfidence

When entrepreneurs conceive a new business idea, they often mistakenly assume their concept is entirely unique with zero direct competitors. This breeds dangerous overconfidence and increases the likelihood of strategic missteps.

3.Setting Goals Beyond Capacity

Understanding potential and setting realistic targets are vital for building a solid work plan. Unrealistic goals lead to financial distress and crush employee morale.

4. Imbalanced Financial Proportionality

Business owners frequently spend either too much or too little, leading to chronic financial instability. Pumping excessive capital into a business prematurely before achieving a reasonable operational scale carries immense risk.

5. Common Hiring Blunders

Startups often default to hiring underpaid, low-skill employees to save short-term cash, only to end up paying much more in the long run due to poor execution. Maintaining the right balance of compensation and talent is critical.

6. Rigid Planning Instead of Adaptive Strategies

Chalking out annual plans purely based on the previous year’s performance is a major pitfall. Because market parameters change rapidly, your business strategy must remain flexible and adaptive.

7. Overlooking Detailed Execution

In the excitement of a new strategy, teams frequently overlook execution details, resulting in chaos. Similarly, operating without a clear grasp of core financial numbers is both unprofessional and misleading.

Lessons from Established Corporate Giants

Even established enterprises make critical errors that impact their finances and reputation:

  • Ignoring Innovation: Big companies often miss opportunities to acquire early-stage disruptors.
  • Being Too Early to Market: Introducing products before the market is ready can backfire. For example, Kodak invented the digital camera in 1977, but it failed commercially because the world wasn’t ready.
  • Algorithmic and Measurement Errors: Even data-driven giants make costly mistakes; NASA once lost $125 million due to a simple unit-of-measurement conversion error.
  • Cash Flow and Saving Discipline: Small and mid-sized entrepreneurs frequently struggle with poor savings habits and cash crunches. While established firms can absorb losses, small businesses rarely survive them without strict financial discipline

Conclusion

No matter how meticulously you strategize, business always carries an inherent element of risk. While risk cannot be completely eliminated, you can prepare for it by maintaining financial stability. Building a robust investment and wealth portfolio is one of the best ways to secure your financial future through every business cycle. Work hard, work smart, and partner with Imperial Money for expert financial guidance.

Note: Mutual Fund investments are subject to market risks, read all scheme-related documents carefully.

Tax Benefits for Senior Citizens in India

Tax Benefits for Senior Citizens in India banner showing a smiling senior couple sitting at a desk with tax planning icons 

The Indian government provides special tax considerations to ease the financial burden on citizens during their retirement years. For tax purposes, individuals aged 60 to 79 are classified as senior citizens, while those aged 80 and above are classified as super senior citizens. Understanding how the tax slabs, exemptions, and deductions apply under both the old and new tax regimes is vital for effective retirement planning.

Download the Mutual Fund Investment App for better retirement planning at  Imperial Money Mutual Fund App.

1. Understanding Income Tax Slabs and Regimes

Taxpayers can choose between different tax structures based on their financial strategy:

  • Old Tax Regime (Age-Based Exemptions): Provides higher basic exemption limits. Senior citizens (60–79 years) enjoy a basic exemption limit of up to Rs. 3 Lakhs with 0% tax, while super senior citizens (80+ years) enjoy an exemption limit of up to Rs. 5 Lakhs.
  • New Tax Regime: Offers standardized tax slabs and exemptions regardless of age, with a higher basic exemption limit and rebates designed to ease tax liabilities.

2. Key Tax Benefits and Deductions for Senior Citizens

Beyond basic exemption limits, senior citizens can claim several specialized deductions and exemptions under the Income Tax Act:

  • Medical Protection and Insurance (Section 80D): Senior citizens can claim deductions up to Rs. 50,000 for health insurance premiums or actual medical expenses incurred (helpful for seniors unable to secure traditional health insurance).
  • Interest Income Exemption (Section 80TTB): Senior citizens are exempt from paying tax on interest earned up to Rs. 50,000 in a financial year from savings accounts, bank fixed deposits, or post office deposits (submitting Form 15H helps prevent TDS deductions).
  • Treatment of Critical Illnesses (Section 80DDB): Senior citizens get an enhanced deduction limit of up to Rs. 1 Lakh for medical treatments related to specified critical or chronic illnesses.
  • Exemption from Advance Tax: Senior citizens who do not have income from a business or profession are exempt from paying advance tax installments, freeing them from quarterly payment pressures and leaving only self-assessment tax when filing.
  • Standard Allowances: Pensioners can claim standard deductions on their pension income to further lower taxable income.
  • Reverse Mortgage Schemes: Monthly installment amounts received by senior citizens under a reverse mortgage plan while retaining home ownership are completely exempt from income tax.

Conclusion

Retirement planning goes beyond just saving; it requires smart tax management to preserve your hard-earned wealth. By leveraging senior citizen tax exemptions, medical deductions, and structured mutual fund investments, you can enjoy a secure, worry-free retirement. Plan your financial future today with Imperial Money.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
GIFT City for Resident Indians: How to Invest in Global Funds (With & Without LRS)

GIFT City for Resident Indians banner showing resident Indians investing in global funds via GIFT City with passport

GIFT City for resident Indians is a way to invest in global markets—US stocks, international mutual funds, ETFs, and more—through a domestic gateway, without opening a foreign brokerage account or routing money through jurisdictions like Mauritius or Singapore. For those researching how to invest in global funds from India, the International Financial Services Centre (IFSC) removes traditional cross-border friction, offering entry points starting from $5,000 under the Reserve Bank of India’s Liberalised Remittance Scheme (LRS).

If you’ve been wanting global diversification but assumed it meant complicated paperwork and a foreign bank account, GIFT City changes that—and a newer route means you may not even need to touch your LRS limit at all.

1. What Is GIFT City and How Do Resident Indians Invest in Global Funds Through It?

GIFT City (Gujarat International Finance Tec-City) is India’s International Financial Services Centre—a zone regulated by the IFSCA, built to function like an offshore financial hub while staying physically and legally connected to India. For resident Indians, it works as a bridge: you invest from India, in most cases using your regular LRS quota, and gain access to global equities, funds, and ETFs that would otherwise require an offshore account.

How Does the Liberalised Remittance Scheme (LRS) Work for GIFT City Investments?

Most GIFT City investments for residents are made under RBI’s LRS, which allows an individual to remit up to USD 250,000 per financial year, per PAN. This limit is cumulative across all LRS purposes—travel, education, gifts, and investments combined—so it’s worth tracking your total usage, not just what you put into GIFT City.

A 20% TCS (Tax Collected at Source) applies on remittances exceeding ₹10 lakh in a financial year, which is refundable/adjustable against your tax liability but affects your cash flow at the time of remittance.

2. Which Global Mutual Funds Can Resident Indians Invest in via GIFT City?

GIFT City mutual funds for Indian investors represent the most user-friendly gateway for everyday investors. GIFT City hosts IFSCA-regulated retail mutual funds—open-ended, with daily NAV, no lock-in—that invest in global markets, often with far lower minimums than you’d expect for an international investment:

  • S&P 500 and Nasdaq 100-linked Fund-of-Funds: Built to mirror these benchmark indices with minimal active management, with several fund houses pricing entry at close to $5,000.
  • Actively managed global equity funds: Diversified 30–40 stock global mandates, offering similarly accessible starting points.
  • Regional and thematic funds: Options covering specific markets or sectors, though minimums here can run considerably higher depending on the fund.
  • Feeder Funds: A slightly different structure worth knowing about: instead of running their own portfolio, feeder funds route your LRS capital into a large, established global master fund (for example, a well-known US or European mutual fund). You get exposure to that master fund’s strategy and track record through a GIFT City-domiciled entry point.
  • Why this matters right now: SEBI caps total industry-wide overseas investment by regular (non-GIFT) Indian mutual funds at USD 7 billion, and several fund houses have restricted fresh global investments as that cap runs close to full. GIFT City for resident Indians provides a vital alternative: because these funds are IFSCA-regulated, not SEBI-regulated, they sit outside that cap entirely—making it one of the few routes still open for fresh global mutual fund investment from India.

3. Can Resident Indians Buy US Stocks Directly Through GIFT City?

Yes, through Unsponsored Depository Receipts (UDRs) listed on IFSC exchanges like NSE International Exchange (NSE IX). UDRs let you buy fractional, dollar-denominated receipts representing shares of companies like Apple, Microsoft, Tesla, or Amazon—directly, without opening a separate foreign brokerage account. The exchange is regulated by the IFSCA, so you get Indian-regulator-level investor protection rather than relying entirely on a foreign platform.

This route has grown quickly, with UDR trading volumes growing roughly ninefold between FY23 and FY25.

4. What Are GIFT City ETFs?

Rather than picking individual global stocks one by one, GIFT City ETFs let you buy into an entire market index in a single, low-cost purchase; common options track the S&P 500, Nasdaq 100, or MSCI World. Beyond these core indices, thematic ETFs are also available, built around specific sectors such as clean energy, artificial intelligence, or global healthcare. For an investor who wants broad global exposure without picking individual funds or stocks, this is often the simplest option.

5. Can Resident Indians Invest in International Bonds Through GIFT City?

GIFT City also offers access to USD-denominated sovereign bonds, global corporate bonds, and green bonds—positioned as a way to diversify away from rupee depreciation risk and earn fixed-income yield in dollars. This can work as a hedge alongside your equity-heavy global allocations, rather than as a standalone strategy.

Availability and minimums for this category can vary by broker and change over time—check current offerings with your GIFT City desk before allocating.

6. Which Global AIF and PMS Options Exist for HNIs?

For investors with larger portfolios, two options go beyond standard mutual funds:

  • Global AIFs (Category I, II, III): Pooled vehicles for private equity, venture capital, real estate, or hedge-fund-style strategies, typically requiring a meaningfully higher minimum investment than retail mutual funds.
  • Global PMS: A dedicated portfolio manager actively manages a bespoke global portfolio of equities, bonds, and ETFs on your behalf, using your LRS funds. This suits investors who want a personalised strategy rather than a pooled fund.

Both are positioned for HNI-level investors—worth discussing with an advisor to see whether the higher entry point makes sense relative to a retail mutual fund or ETF route.

7. Investing in Global Funds Without Touching Your LRS Quota?

This is genuinely one of the more useful developments for investors outside major metros. Some domestic Indian mutual fund houses now offer rupee-denominated funds that invest in underlying GIFT-listed international ETFs—you buy units through your regular domestic demat account, in rupees, with no LRS remittance involved at all.

The trade-off: under current tax rules, such funds are generally taxed as non-equity funds—gains are taxed at your income slab rate rather than the more favourable equity LTCG rate. Still, for a first-time global investor who wants simplicity over the lowest possible tax rate, it removes the remittance paperwork entirely.

8. How Do You Actually Park Funds for GIFT City Investing?

You can also open a foreign currency account with an IFSC Banking Unit (IBU) and remit your LRS quota there in USD, GBP, or EUR—once. From there, you can deploy into different GIFT City products as opportunities arise, instead of remitting money separately (and paying forex markup) for every individual investment.

9. GIFT City Global Investment Options at a Glance

Product
Route
Typical Minimum
Best for
LRS
~$5000
Retail Investors wanting simple low ticket global exposure
Feeder funds
LRS
Varies by fund
Investors who want exposure to an established global master fund
UDRs — direct US stocks
LRS
Fractional, varies by broker
Investors who want to own specific US stocks directly
GIFT City ETFs
LRS
Generally low
Low-cost, single-instrument global index exposure
International bonds
LRS
Varies by broker
Investors seeking USD fixed income as a currency hedge
Global AIFs & feeder AIFs
LRS
HNI-level
Investors seeking private equity, VC, real estate or hedge-fund strategies
Global PMS
LRS
HNI-level
Investors wanting a bespoke, actively managed global portfolio
Domestic rupee-wrapper funds
No LRS used
Regular mutual fund minimums

Minimums vary by AMC/broker and change over time — treat these as indicative starting points, not fixed figures.

Frequently Asked Questions

  • Can I invest in GIFT City without an NRE or NRO account?
    Yes. All transactions occur via dedicated foreign currency accounts within the IFSC, completely independent of domestic NRE or NRO banking mechanisms.
  • How secure is capital invested through GIFT City?  
    Every institution in the zone is authorized and monitored by the IFSCA, a statutory body created by the Government of India that enforces international standards of investor protection and transparency.
  • Will I owe capital gains taxes on IFSC trades?
    Transactions involving qualifying securities conducted on approved IFSC exchanges are 100% exempt from Indian capital gains tax. Specific pass-through fund rules vary, so always confirm at the scheme level.
  • Are funds held in GIFT City freely repatriable?
    Yes. Principal capital, dividends, interest, and realized gains can be transferred back to your overseas bank accounts without domestic remittance restrictions.
  • Do non-residents need to file an Indian tax return for IFSC investments?  
    For designated tax-exempt assets held strictly inside the IFSC, non-residents are typically exempt from both obtaining an Indian PAN card and submitting annual income tax returns, provided standard onboarding KYC is complete.

Thinking About Adding Global Exposure to Your Portfolio?

Every global Indian navigates unique double-tax treaties, local tax brackets, liquidity targets, and long-term currency objectives. Our wealth advisory team can help you identify the optimal balance of foreign currency deposits, curated funds, and tax-exempt insurance structures.

How to Make Yourself Debt-Free Quickly & Build Portfolio

How to Make Yourself Debt-Free Quickly & Build Portfolio banner with coin stacks, plant jars, and logo. 

Living with mounting debt can feel emotionally and financially draining. While secured loans like home or car loans are manageable, falling into high-cost debt traps—such as credit card balances or high-interest market borrowings—can easily exceed your repayment capacity. Escaping this cycle requires firm commitment, strict self-discipline, and a structured action plan. 

Download the Imperial Money Mobile App for managing your portfolio and tracking your financial goals.

1. Gather Your Financial Data

The first and most critical step is gathering comprehensive data about your financial standing. Obtain copies of your credit reports, check your credit score, and collect recent statements for all your existing obligations, including:

  • Student loans
  • Personal loans
  • Mortgage loans
  •  Credit card balances

Reshape your attitude toward money by avoiding new loans or unnecessary expenses until your existing liabilities are cleared.

2. Build a Comprehensive Financial Inventory

Compile your debts into a clear inventory to power your debt-busting strategy:

  • Add up the total sum of all your outstanding debts.
  • Decide on a realistic target number of months for repayment.
  • Divide the total balance by your target months to establish a fixed monthly payoff figure.
  • Commit to settling that exact amount every single month.

3.Track Your Spending Diligently

To eliminate debt quickly, you must understand exactly where every rupee goes. Make necessary budget cuts by tracking monthly bills and daily spending, factoring your debt obligations directly into your tracking list. Use budget worksheets, handwritten notes, banking app trackers, or physical receipts to maintain total clarity.

4. Cut Unnecessary Expenses

Balance your income by drastically curbing non-essential outflows. Evaluate recurring expenses like subscription fees or lifestyle upgrades—every penny saved accelerates your debt repayment plan. You can always re-evaluate optional spending once your debts are fully cleared.

5. Establish an Emergency Fund and Seek Professional Help

Building a small emergency fund acts as a financial shield against unforeseen crises. Financial experts recommend keeping at least six months’ worth of living expenses saved. Additionally, do not hesitate to seek professional debt counseling. At Imperial Money, we provide expert debt consultation and management plans to help you regain financial literacy, reduce your liabilities, and transition smoothly into wealth building.

Learn how to build a robust investment portfolio on our Imperial Money YouTube Channel.

Conclusion

Escape from the debt trap is entirely possible with disciplined spending adjustments and effective professional guidance. Resolve your worries, eliminate your liabilities, and start building a secure investment portfolio today with Imperial Money.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
GIFT City for NRIs: A Complete Guide to Investment Products and Tax Benefits

 GIFT City for NRIs Your Global Gateway to India's Growth Story with modern skyline and logo. 

GIFT City for NRIs offers a streamlined gateway to invest in India-linked opportunities entirely in foreign currency, accompanied by tax treatment that often outpaces both foreign jurisdictions and the domestic Indian market. Whether allocating to foreign-currency bank accounts, offshore mutual funds, dollar-backed policies, private funds, or exchange-traded equities, GIFT City investment for NRIs bypasses conventional red tape: most assets eliminate the need for an Indian PAN card and carry zero capital gains tax on IFSC exchange transactions.

For global Indians weighing a GIFT City vs NRE NRO account approach to escape persistent rupee depreciation, endless notarized documentation, and domestic tax filing obligations, this ecosystem warrants a close look.

1. GIFT City Explained: What Makes It a Smart Move for NRIs?

Situated in Gujarat, GIFT City operates as India’s dedicated International Financial Services Centre (IFSC). From a regulatory and fiscal standpoint, the zone functions as an autonomous, foreign-currency offshore territory established directly on Indian soil. Built along the regulatory blueprints of hubs like Singapore and DIFC Dubai, the zone conducts business exclusively in freely convertible currencies, operates under an independent unified regulator (IFSCA), and enforces tax exemptions engineered for non-resident capital.

For global Indians evaluating GIFT City for NRIs, the primary benefit comes down to simplicity: participating in India’s capital expansion and overseas markets using global currencies, completely bypassing rupee conversion channels.

2.GIFT City vs NRE NRO Account: Banking Products Available

Through IFSC Banking Units (IBUs), non-residents can establish foreign-currency transactional and savings accounts denominated in major currencies including USD, GBP, and EUR.

Should NRIs Consider a GIFT City Fixed Deposit?

When it comes to low-risk treasury and liquidity management, setting up a GIFT City fixed deposit for NRI portfolios remains the most popular starting avenue. Available across tenures ranging from 7 days up to 5 years, these term deposits guarantee full repatriation of both initial capital and accrued yields, alongside complete freedom from Indian income tax. With select IFSC banking units setting account opening minimums between USD 500 and USD 1,000, capitalizing on the practical benefits of a GIFT City fixed deposit for NRIs gives savers a straightforward entry point before stepping into market-linked instruments.

3. Dollar-Denominated Insurance in GIFT City: What's on Offer for NRIs?

A standout component of GIFT City for NRIs is dollar-denominated insurance, where branches of top-tier carriers—known as IFSC Insurance Offices (IIOs)—issue term coverage, savings plans, and ULIPs settled entirely in foreign currencies.
A key statutory advantage under recent fiscal guidelines shields non-residents from Indian taxation on both policy maturity payouts and death benefits. Furthermore, insurance premiums paid within the IFSC remain exempt from GST. This structure allows overseas professionals to fund long-term commitments—such as international university fees for children or foreign healthcare contingencies—in US dollars without losing yield to domestic tax withholdings.

4. Fund & Asset Management in GIFT City for NRIs

The available fund universe spans three primary vehicles:

  • Mutual Funds & Feeder Strategies: Dollar-based portfolios designed to route foreign capital into high-performing onshore domestic strategies, allowing investors to participate without holding local rupee accounts. Select retail-focused funds accept initial tickets starting at $500.
  • Alternative Investment Funds (AIFs): Encompassing Category I, II, and III licenses, these pooled vehicles focus on venture capital, private equity, structured debt, and long-short market strategies. They cater specifically to accredited HNIs pursuing sophisticated, non-correlated market strategies.
  • Portfolio Management Services (PMS): Tailored, actively managed mandates designed for HNIs and family offices, managed in foreign currency with custom mandates and dedicated portfolio managers.
  • Regulatory Development: Streamlined cross-border migration rules allow legacy offshore funds and ETFs domiciled in places like Mauritius or Ireland to re-domicile directly into GIFT City without triggering capital gains taxes, steadily expanding the selection of institutional funds.

5. Direct Trading: Equities and Debt Securities

Investors can trade directly on international trading desks such as NSE IX and India INX through registered IFSC brokers. The platforms support cross-border equities, global ETFs, and index futures (including GIFT Nifty) settled in foreign currency, removing the need for a domestic INR demat or trading account.

In the debt market, IFSC bond desks provide steady fixed income through dollar-denominated corporate paper and offshore rupee-linked “Masala bonds” floated by Indian blue-chip companies raising international debt.

6. Key Tax Benefits of GIFT City for NRIs

Tax Category / Charge
Domestic Indian Market
GIFT City (IFSC)
12.5% LTCG / 20% STCG
0%
Securities Transaction Tax (STT)
Levied on all transactions
0%
Stamp Duty
Standard domestic rates
0% (Eligible Securities)
Tax on Insurance & ULIP Maturity Proceeds
Taxed beyond threshold limits
0% (Non-Residents)
Tax on Foreign Currency Deposit Interest
Subject to account classification
100% Tax-Exempt
PAN Card Obligation
Compulsory
Generally Not Required for specified IFSC holdings

Note: Overseas tax implications rest on your personal residency status and the relevant Double Taxation Avoidance Agreement (DTAA) in your home jurisdiction. Review your personal profile with a qualified tax strategist

7. Regulatory Oversight and Investor Protection

Financial activities within the center fall under the jurisdiction of the International Financial Services Centres Authority (IFSCA). Rather than navigating separate regulatory touchpoints across RBI, SEBI, and IRDAI, market participants operate under this single unified body. The IFSCA maintains strict governance frameworks, capital adequacy mandates, and fast-track grievance redressal mechanisms aligned with tier-one global financial capitals.

8. Getting Started: How NRIs Can Begin Investing in GIFT City

  • Determine Your Asset Strategy: Pinpoint whether your portfolio requires conservative cash parking (FDs), long-term life cover, or equity growth engines (Mutual Funds, AIFs, PMS).
  • Submit Paperless KYC: Complete remote identity verification using your current passport, overseas proof of residence, and standard client declarations.
  • Credit Your IBU Account: Wire funds directly from your local overseas bank account in USD, EUR, or GBP.
  • Allocate Capital: Select and execute your asset mix in convertible currencies alongside your wealth manager.

Frequently Asked Questions

  • Can I invest in GIFT City without an NRE or NRO account?
    Yes. All transactions occur via dedicated foreign currency accounts within the IFSC, completely independent of domestic NRE or NRO banking mechanisms.
  • How secure is capital invested through GIFT City?  
    Every institution in the zone is authorized and monitored by the IFSCA, a statutory body created by the Government of India that enforces international standards of investor protection and transparency.
  • Will I owe capital gains taxes on IFSC trades?
    Transactions involving qualifying securities conducted on approved IFSC exchanges are 100% exempt from Indian capital gains tax. Specific pass-through fund rules vary, so always confirm at the scheme level.
  • Are funds held in GIFT City freely repatriable?
    Yes. Principal capital, dividends, interest, and realized gains can be transferred back to your overseas bank accounts without domestic remittance restrictions.
  • Do non-residents need to file an Indian tax return for IFSC investments?  
    For designated tax-exempt assets held strictly inside the IFSC, non-residents are typically exempt from both obtaining an Indian PAN card and submitting annual income tax returns, provided standard onboarding KYC is complete.

Ready to explore GIFT City for NRIs and structure your portfolio?

Every global Indian navigates unique double-tax treaties, local tax brackets, liquidity targets, and long-term currency objectives. Our wealth advisory team can help you identify the optimal balance of foreign currency deposits, curated funds, and tax-exempt insurance structures.


Are You Preparing Yourself For The Big Opportunities In Investments

Are You Ready For Investments banner showing people putting money into a large piggy bank with Imperial Money logo

India is a rapidly developing nation where roughly 50% of the population belongs to the working class. While millions earn only enough to cover basic survival needs, millions more possess surplus capital to save for the future. Traditionally, Indians relied on goods or safe bank instruments like Fixed Deposits (FDs). However, with inflation hovering around 4% to 5% and bank returns capped at 6% to 7%, traditional savings leave very little margin for genuine wealth growth. To stay ahead, transitioning from passive saving to smart investing is essential.

Download the Imperial Money Mobile App to fulfill your long-term and short-term financial goals.

1.Preparing Your Mind for Investment and Managing Risk

Investment inherently involves risk, but building a risk appetite takes time and does not mean throwing caution to the wind. The foundational equation of investing is straightforward: high risk yields high returns, while low risk offers modest gains. For beginners seeking a safe yet high-yielding middle ground, mutual funds provide an ideal vehicle by pooling capital to invest across multiple companies under the guidance of professional fund managers.

2. The Power of SIPs Over Traditional Deposits

While Recurring Deposits (RDs) offer predictable returns of 6% to 7%, Systematic Investment Plans (SIPs) in mutual funds allow investors to channel fixed amounts regularly into diversified portfolios, historically delivering superior annual returns exceeding 10%. SIPs offer affordability, flexibility, and a structured way to invest without trying to time the unpredictable market. 

3.Overcoming Market Timing Concerns

Many investors hesitate, searching for the “right time” to enter the market. Because mutual funds are inherently diversified, they are insulated from the perils of trying to time individual stocks perfectly. There is no right or wrong time to begin investing through a disciplined approach.

4.The Value of Professional Guidance

Choosing the right fund can be tricky, which is why verified guidance from an expert advisory firm and a skilled fund manager is invaluable. Imperial Money Private Limited offers personalized financial services—spanning mutual funds, wealth creation, estate planning, and insurance—to help you navigate the markets effortlessly.

Conclusion

Handling money smartly is the need of the hour in a booming economy. Beyond mutual fund investments, securing a comprehensive future for your loved ones requires careful consideration of insurance, estate planning, and overall financial management. Plan your investments wisely today to build a prosperous tomorrow.
Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
Cryptocurrency vs Mutual Funds: Where Should You Invest?

Cryptocurrency vs Mutual Fund banner comparing Bitcoin tokens with a golden bull on a keyboard.

The concept of currency has evolved dramatically over millennia, transitioning from primitive trade systems to coins, paper notes, and complex digital structures. This evolution drives modern investors to seek assets that preserve purchasing power and generate long-term wealth. Among the most discussed vehicles today are traditional mutual funds and decentralized cryptocurrencies. Understanding their underlying differences is essential before deploying your hard-earned money.

1. What Is a Mutual Fund and How Does It Work?

A mutual fund is a professionally managed financial vehicle that pools capital from multiple investors to invest in a diversified basket of securities, such as stocks, bonds, money market instruments, and real estate. Professional fund managers oversee the portfolio to maximize returns, with any gains or losses proportionally shared among the shareholders.

2.What Is Cryptocurrency and How Does It Work

Cryptocurrency is a decentralized digital currency utilizing peer-to-peer networks and blockchain technology without a governing central authority. Digital assets like Bitcoin or Ethereum are typically limited in supply and generated through complex computational mining. While proponents view crypto as a futuristic store of value, its underlying mechanisms and market structures differ vastly from traditional asset classes.

3. Comparing Mutual Funds and Cryptocurrencies

Parameters
Mutual Funds
Cryptocurrency
Source / Quantity
Backed by existing underlying corporate assets and economic value.
Finite in total supply and dependent on digital mining protocols
Risk Profile
Comparatively low to moderate risk, regulated and structured.
High risk due to extreme market volatility and uncertainty.
Historical Returns
Steady annualized returns typically ranging between 5% – 15%.
Highly volatile performance fluctuating wildly across market cycles.
Additional Costs
Low expense ratios and minimal transactional fees.
Low network transactional fees, but subject to heavy tax burdens.
Medium of Investment
Accessible through licensed financial advisors or digital platforms.
Traded online via specialized crypto exchanges and applications.
Legal Status in India
Fully legal and heavily regulated by SEBI
Legal to own and trade, but classified as Virtual Digital Assets (VDAs) rather than legal tender.

This shows that you don’t need ₹100 crore today — you need a strategy to build it over time.

4. Market Concentration and Volatility in Crypto

Cryptocurrency markets are heavily influenced by whale accounts and concentrated holdings. Global tracking shows that a tiny fraction of accounts control a major percentage of total circulating Bitcoin, leaving the market highly vulnerable to extreme price swings driven by single-holder transactions.

5. Aligning Investments with Your Risk Appetite

There is no universal “winner” between mutual funds and crypto; their compatibility depends entirely on your personal risk tolerance and financial goals. Because crypto operates with high uncertainty and lacks traditional consumer protection frameworks, choosing sensible, realistic products aligned with your risk profile is vital. Furthermore, meticulous financial planning and professional guidance remain critical.

Conclusion

Investing requires a clear strategy that honors your capacity to manage risk and absorb market outcomes. Whether you choose structured mutual funds or alternative digital assets, consulting with an expert financial distributor ensures your capital is handled safely. Imperial Money Private Limited specializes in personalized wealth creation, mutual fund distribution, and systematic investment solutions designed to help you achieve long-term financial freedom.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
Why Mutual Fund Investments Are Important for Indian Women Investors

Women are natural wealth organizers and financial experts by virtue of life experience. The inherent traits required for long-term market success—patience during volatility, sacrifice of short-term temptations, dedication to nurturing holdings, and multitasking under pressure—mirror the natural strengths women exhibit every day. Yet, historical data shows a significant gap: studies indicate that a large percentage of women in India remain unengaged or underinvested in financial markets, often due to a lack of targeted knowledge rather than capability. Bridging this gap is essential for personal empowerment and generational wealth.

1. Moving Beyond Traditional Savings

Historically, many Indian women have relied solely on traditional savings accounts or fixed deposits. While these tools offer safety for emergency funds, their low post-tax yields often fail to outpace inflation, leading to a silent erosion of purchasing power. Transitioning working capital into growth-oriented vehicles like mutual funds is vital to achieving real wealth accumulation.

To know more about investment and start your journey, download the App

2. Key Advantages of Mutual Funds for Women Investors

  • Financial Independence: Achieving financial independence ensures you have the resources to support yourself and your family independently, eliminating reliance on external sources for basic needs and life choices.
  • Long-Term Security: A robust investment corpus acts as a reliable safety net against unexpected life events, job transitions, or medical emergencies, providing total peace of mind.
  • Complete Control and Freedom: Managing your own investments gives you absolute authority over your cash flow, debt management, and future aspirations. Freedom from financial anxiety unlocks the confidence to make independent life decisions.
  • Enhanced Self-Respect and Relationships:Being self-sufficient fosters deep personal confidence and earns societal respect. Furthermore, financial security removes monetary stress from family dynamics, fostering healthier and more transparent relationships.

Conclusion

It is time to shatter the outdated myth that investing is exclusively a man’s domain. In reality, the emotional discipline, patience, and long-term vision possessed by female investors make them exceptionally well-suited for stock market and mutual fund success. By taking the first step with modest, consistent SIPs, women across India can take the lead, secure their financial futures, and build lasting legacies.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
Power of Compounding in Mutual Fund

The Power of Compounding in Mutual Fund graphic with rising coin stacks and green saplings showing growth.

Everyone prefers an exciting life full of rewards rather than a plain, routine existence, and your investment returns should be no different. The rate of return on your investments—often measured by CAGR—provides that excitement. Compound interest causes your investments to grow substantially over time, meaning even modest initial amounts can result in massive wealth generation if given a long-term horizon of 10 years or more.

1. What Is the Power of Compounding?

The power of compounding refers to earning interest on your previous interest. When your earnings are added back to the original principal, that new total becomes the basis for the next cycle. This snowball effect dramatically accelerates asset growth over time. For example, investing Rs. 1,000 at a 10% annual return yields Rs. 1,100 after the first year, Rs. 1,210 after the second year, and continues compounding exponentially.

2. How Compounding Powers Mutual Funds

Compounding in mutual funds is one of the most impactful wealth-creation tools available. If you invest Rs. 1,000 and earn Rs. 50 in compound growth, the next cycle calculates profit on Rs. 1,050 rather than the original Rs. 1,000. This engine builds your corpus tremendously rather than just gradually.

3.The Magic of Compounding via SIP (Systematic Investment Plan)

SIP investments allow you to seamlessly harness the power of compounding. By investing small, pre-determined amounts regularly, you avoid trying to time the market while building a disciplined habit. For instance, investing Rs. 5,000 per month for 15 years at an expected 12% annual return can help you accumulate an impressive wealth corpus of Rs. 25,22,880 (based on monthly compounding).

4.Why Long-Term Consistency Matters

The true multiplier of compound growth is time. Because mutual fund units are purchased dynamically each month depending on market conditions, staying consistent over a long period allows compounding to work at its maximum capacity.

Conclusion

Compounding is one of the greatest wealth-building mechanisms available to modern investors. Take advantage of the power of compounding and begin your structured mutual fund investing journey right away with Imperial Money.

Note: Mutual Fund investments are subject to market risks, read all scheme-related documents carefully.