Who Do You Listen

Two boys were once traveling through a jungle when they came across a well, and the elder boy accidentally fell inside while drawing water. Panicking and finding no one around to help, the younger boy threw a rope down and managed—through sheer effort and determination—to pull his older friend out of the well. 

How was a child able to accomplish such an extraordinary feat? Because there was nobody around to tell him that he was too small for the task. It is environmental noise and discouragement from others that so often puts the brakes on our true potential.

Download the Imperial Money Mutual Fund App to start building your wealth today.

1. The Parable of Noise in Personal Finance

This story carries a profound lesson for personal finance and investing. Many investors panic and redeem their investments prematurely simply due to the influence of the people around them. The moment the market turns uncertain or volatile, external voices flood our minds with warnings to pull out or risk losing everything.

2. Overcoming Environmental Noise

  • This environmental noise breaks our determination to hold our investments for the long term. Statistics show that only 2% of people hold their investments for over 10 years to truly reap the massive benefits of long-term compounding. If investors could tune out the surrounding noise—just like the young boy who had no one to tell him he couldn’t succeed—a much larger percentage of people would stay the course and generate life-changing returns.

Conclusion

Never let external market noise or uninvited advice derail your financial goals. By tuning out the chatter, staying disciplined, and partnering with experienced advisors at Imperial Money, you can maintain your conviction and achieve true financial independence.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
What is the Similarity between Teabag and Mutual Fund Investment Bag

Invented by Thomas Sullivan in 1908, the teabag revolutionized how we enjoy tea, just as Abraham van Ketwich’s creation of mutual funds in the 18th century revolutionized global wealth building. While a teabag and a mutual fund investment might seem unrelated at first glance, they share surprising and profound similarities when it comes to quality, flavor, and financial growth.

Download the
Imperial Money Mutual Fund App to start your investment journey today.

1. Quality Depends on the Contents, Not the Packaging

A teabag’s true value lies entirely in the quality of the tea leaves inside, not the outside packaging. Similarly, the quality of your financial returns depends entirely on *how* and *where* you invest your money. Selecting the right, fundamentally sound investment plans is essential to securing bigger profits.

2.True Flavor Emerges Under Pressure

Just as a teabag releases its rich taste only after being steeped in hot water, true financial profits and returns are forged when your investments pass through adversity, pressure, and volatile market atmospheres. Navigating market downturns successfully delivers long-term profitability.

3.Porosity and Transparency Matter

Teabags must be porous and transparent to let the tea dissolve seamlessly into water or milk. Similarly, your investments must be transparent with proper asset allocation. A clear, well-structured portfolio ensures a higher percentage of profitable returns.

4. Consistent Performance Across All Situations

A teabag gets its job done regardless of how or where it is placed in the cup, delivering the exact same quality of taste. Likewise, building a robust, diversified portfolio with proper asset allocation and periodic rebalancing ensures maximum returns and stability across various market conditions.

5. Scaling Resources to Match Your Goals

If you are brewing a large pot of tea, you need more teabags. Similarly, if your life objectives and retirement goals are grand, you need a disciplined, larger volume of structured investments to fulfill them. Ultimately, just as good tea requires the right balance of milk and sugar, achieving optimal returns requires partnering with an expert financial advisor like Imperial Money.

Conclusion

Great tea comes down to the quality of the brew, and great wealth comes down to expert guidance and disciplined asset allocation. Let Imperial Money guide you on your path to financial freedom and wealth creation.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
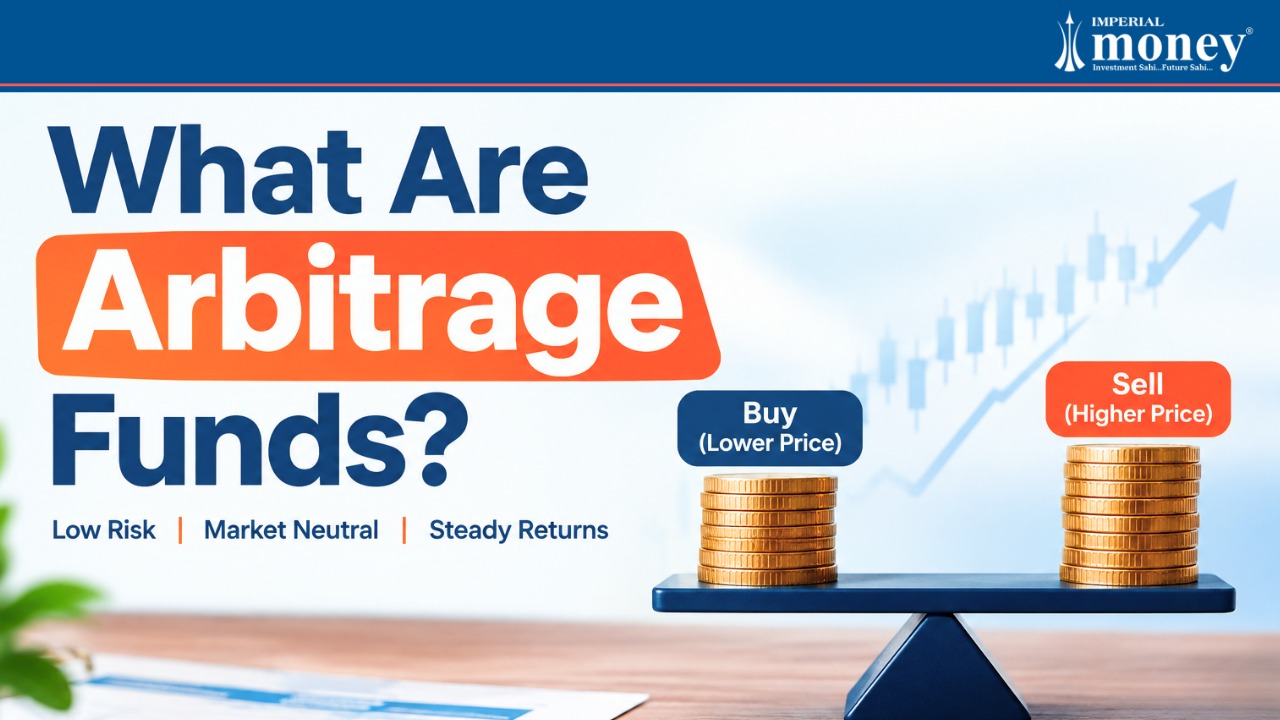
What Are Arbitrage Funds?

Arbitrage funds are unique hybrid mutual funds that capitalize on market inefficiencies by taking arbitrage positions in equity and equity-related instruments for at least 65% of their portfolio. The remaining corpus is typically deployed in high-quality fixed-income instruments, cash, and cash equivalents, providing a balanced vehicle for conservative investors looking for smart tax efficiency.

1. How Arbitrage Funds Work

Arbitrage funds aim to capture the price differential between the spot market and the futures market. The mechanism functions through specific principles:

  • Simultaneous Buy and Sell: These funds buy securities in the lower-priced spot market and simultaneously sell them in the higher-priced futures market.
  • Capitalizing on Spreads: The price spread between spot and futures markets typically reflects money-market rates, widening during periods of high volatility to create lucrative opportunities.
  • No Reverse-Arbitrage: By mandate, these funds cannot engage in reverse-arbitrage (selling shares and buying futures). While daily mark-to-market valuations can sometimes cause temporary fluctuations or negative returns before contract expiry, positions are reversed and profits locked in at the expiration of the futures contract.

2. Ideal Investment Horizon and Suitability

Arbitrage funds are best suited for investors with a horizon ranging from 3 to 6 months, particularly during volatile market phases. Because they invest over 65% of their portfolio in hedged arbitrage opportunities, they expose investors to lower credit risk compared to standard liquid funds.

3. Favorable Tax Advantages

While pre-tax returns on arbitrage funds are comparable to those of liquid funds, their equity-oriented tax structure yields significantly higher post-tax returns:

  • Short-Term Holdings (Up to 1 Year): Taxed at a flat rate of 15% (plus applicable cess and surcharge), compared to the 30% slab rate applied to liquid and debt funds for investors in the highest tax bracket.
  • Long-Term Holdings (1 to 3 Years): Gains are taxed at only 10% on excess gains above Rs. 1 lakh, compared to 30% for high-bracket investors in traditional debt vehicles.

Conclusion

Arbitrage funds offer a smart, low-credit-risk alternative for investors seeking stability combined with superior post-tax efficiency. Explore how arbitrage funds can fit into your portfolio by connecting with our expert advisors at Imperial Money.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
How to Choose Mutual Funds for Yourself?

With over a thousand open-ended equity and debt funds offered across more than 50 asset management companies in India, selecting the right fund can feel like an enormous challenge. Many investors rely blindly on star ratings, which often act more like lagging indicators than true guides. To build a robust portfolio that aligns with your financial goals, time horizon, and risk appetite, you need to examine both quantitative metrics and qualitative fundamentals.


1. Evaluate the Asset Management Company (AMC) Pedigree

Evaluating a fund house goes beyond short-term performance numbers. A premier distributor looks at top-down factors: whether the fund house acts in investor interests, maintains regulatory compliance, and possesses stable ownership and management. Prioritizing institutional stability ensures your investments are backed by a robust, process-driven framework rather than a single individual

2. Prioritize Risk Management and Credit Safety

Recent credit events and liquidity shocks in fixed-income markets have highlighted the importance of rigorous risk management. Dedicated, independent risk-management teams ensure that fund managers operate within strict boundaries. For debt investors seeking a margin of safety, choosing conservative fund houses with clear, predictable styles helps mitigate credit and liquidity risks

3.Assess Ethics and Total Expense Ratios (TER)

Honesty and investor-first principles are crucial. Avoid AMCs that prioritize increasing their own bottom-line profits over investor returns—such as those failing to lower their Total Expense Ratios (TER) when performance slips. Partner with transparent fund houses that genuinely look out for their investors.

4. Focus on Current Portfolio Positioning Over Past Performance

Past performance is no guarantee of future returns. Instead of falling into the trap of high ratings, analyze the fund’s current portfolio holdings and the fund manager’s strategic thought process. This reveals how the fund is positioned to capture future opportunities.

5. Watch Fund Size (AUM) and Regular Inflows

While fund houses often claim size doesn’t matter, historical analysis shows that overly large funds can struggle to beat nimbler peers. At Imperial Money, we prefer optimal fund sizes—for instance, avoiding multi-cap funds above Rs. 3,500 crores, mid/small-cap funds above Rs. 2,000 crores, and large-cap schemes exceeding Rs. 5,000 crores. Furthermore, consistent regular inflows indicate that investors have strong conviction in the fund manager’s philosophy.

6. Know When to Say Goodbye to a Fund

No fund outperforms indefinitely. While short-term dips can be ignored, steady underperformance over a prolonged period (such as monitoring for a year) is a clear red flag, signaling that it is time to halt fresh allocations or exit the scheme.

Conclusion

Picking the correct mutual fund is both an art and a science. By looking beyond surface-level ratings, evaluating AMC pedigree, monitoring portfolio composition, and practicing disciplined asset allocation, you can build a secure financial future. Connect with Imperial Money to get expert guidance tailored to your investment goals.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
How to Get Back Your Home Loan Interest Amount?

For most individuals, purchasing a dream home involves taking a massive home loan, turning the monthly interest payout into one of their largest expenses. Banks function as modern financial institutions, and during the first few years of a loan, the vast majority of your EMI goes toward paying off interest while the principal remains virtually stagnant. However, with smart financial planning, you can tackle this burden head-on.

Download the Imperial Money Mutual Fund App to start building your wealth today.

1. How to Reduce Your Interest Burden

The first step is to negotiate directly with your lending institution or bank manager to lower your home loan interest rate, which will subsequently reduce your monthly EMI and heavy interest outflows.

2. How to Get Back Your Interest Amount (Achieving a 0% Effective Home Loan)

The most powerful solution to recover the interest you pay is parallel investing. For example, if your average EMI for a Rs. 50 Lakh home loan is Rs. 42,000, you can start a simultaneous **Systematic Investment Plan (SIP)** in mutual funds aiming for an expected 12% return. Over time, the returns generated from your mutual fund investments can completely recover the total interest amount you pay on your home loan, effectively making your dream home interest-free.

3.How to Buy a Home with an Interest-Free Corpus

If your goal is to buy a luxurious house worth Rs. 1 Crore, consider extending your home-buying timeline by 10 years and deploying your capital into lumpsum or systematic mutual fund investments targeting a 12% return. By the end of the decade, the accumulated cash corpus allows you to purchase your dream house entirely in cash—completely eliminating the headache of home loan interest rates and EMIs.

4.Creating Wealth Out of a Home Loan

The true multiplier of compound growth is time. Because mutual fund units are purchased dynamically each month depending on market conditions, staying consistent over a long period allows compounding to work at its maximum capacity.

Conclusion

A home loan doesn’t have to drain your financial life. By reducing your interest rates, recovering your interest through disciplined mutual fund SIPs, and planning your asset allocation with Imperial Money, you can enjoy your dream home without the crushing weight of loan interest.

Note: Mutual Fund investments are subject to market risks, read all scheme-related documents carefully.

Entropy!!! Why You Should Know this

Formulated by physicists like Ludwig Boltzmann and Rudolf Clausius in the nineteenth century, entropy measures the amount of energy that escapes or becomes unavailable during a process. Whether observing ice melting into warm water, fruit rotting on a table, or the relentless ticking of the “time arrow,” physical decay is irreversible. In life and finance, the philosophy remains the same: time lost cannot be reclaimed, and failing to plan means missing your target.

Looking to invest? Download the Imperial Money Mutual Fund App.

1. The Reverse Entropy of Systematic Investment Plans (SIPs)

While natural entropy governs decay and irreversibility, a Systematic Investment Plan (SIP)  works in the exact opposite fashion. An SIP starts out looking modest, but over time it accelerates wealth creation so rapidly that it can be hard to imagine. 

  • The Cost of Delay: Delaying your investment by just 1 year can destroy up to 10% of your 20-year wealth corpus. For example, investing Rs. 5,000 monthly at a 12% return over 20 years builds a corpus of roughly Rs. 46 lakhs. Delaying that start by a single year leaves you with only about Rs. 40 lakhs after 19 years.
  • Time is Irreversible: Just like you cannot un-melt ice without expending brand-new energy, time lost cannot be reversed. Once the arrow of time flies, it cannot be recalled.

2. Overcoming Financial Entropy and Obsolescence

Entropy dictates that unmaintained systems naturally decay. In the corporate world, failing to adapt to new methods or modern financial vehicles—such as sticking blindly to low-yield fixed deposits instead of shifting to growth-oriented mutual funds—can lead to total obsolescence, much like once-dominant legacy corporations that failed to adapt and collapsed.

3.Can Entropy Be Overcome?

In a cosmological sense, no—the universe moves toward decay. However, in our personal lives and financial planning, there is a definitive solution: **staying dynamic**. 

  • Injecting fresh capital, new technologies, creative thinking, and strategic imagination can turn personal finances, careers, and organizations around.
  • Thinking outside the box for your investments and moving away from stagnant assets protects you against financial decay.

4.Guarding Against Complacency

Entropy always exists and requires constant vigilance. The moment we lower our guard or become complacent in our wealth management, the decay of our financial health begins. Proactive planning and structured investing are your greatest defenses against the forces of entropy.

Conclusion

What is done cannot be undone, but you can control your future target through deliberate planning. Take advantage of the power of compound growth, beat financial entropy, and begin investing in mutual funds right away with Imperial Money.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
5 Unknown Winning Stocks Trading Ideas

With millions of new Demat accounts opening and social media channels flooded with stock tips from overnight investing gurus, retail trading has never felt more accessible. However, navigating a highly volatile market requires much more than casual advice. Achieving extraordinary results doesn’t require complex maneuvers; instead, it demands a disciplined, robust 5-point fundamental framework.

Open a free Demat account instantly with Imperial Money

1. Understand the Business Thoroughly

Never rush into buying a stock without fully understanding the underlying business model. Treat individual stocks as small ownership pieces of a real company—when the business succeeds, the stock naturally follows. Know the core product line-up and monitor sector trends. For instance, during health crises or economic shifts, defensive sectors like pharma (e.g., Cipla, Glenmark, Syngene, Biocon) or IT offer resilience and growth.

2. Be Precise and Avoid Over-Diversification

Avoid holding 20 to 80 random stocks in your portfolio. As the saying goes, excess in anything is poisonous. Maintain a focused portfolio where individual stocks carry a 10% to 15% equal weight (or 20% to 25% if your total capital is smaller). A highly concentrated portfolio built on strong convictions is often the mark of a disciplined business-minded investor.

3.Practice Disciplined Diversification

Ensure proper sector diversification across your portfolio—such as allocating around 20% to distinct sectors. Crucially, always hold a cushion of defensive stocks during turbulent scenarios to maintain liquidity and keep your portfolio floating against market volatility.

4. Seek Authenticity and Guidance

Look for advisors who embody three essential qualities: Integrity, Intelligence, and Energy, with integrity being non-negotiable. Every investor needs handholding during market drawdowns. Engaging with authentic groups and trusted advisors—such as Imperial Money—provides the psychological confidence needed to hold quality stocks even when they dip 10% or more.

5. Rotate Assets and Book Profits Systematically

Maintain a disciplined approach to profit booking. Booking profits when stocks hit a 10% to 15% gain allows you to keep capital moving alongside cyclical trends. Rotating your money 5 to 6 times a year through disciplined reinvestment multiplies your annual returns effortlessly. While technical charts help time entries, fundamental strength remains the anchor of any successful trading model.

Conclusion

Successful trading and investing require patience, discipline, and a sound strategy. If you want to learn more about our investment philosophy or need expert stock advisory solutions, our team at Imperial Money is here to help. Our dedicated fundamental and technical analysts work tirelessly to bring you the best market insights and wealth-building ideas.

Note: Mutual Fund and stock investments are subject to market risks; read all scheme-related documents carefully.

Capital Gain on Sale of Immovable Property by NRI

For Non-Resident Indians (NRIs), selling immovable property in India often brings confusion regarding tax liabilities. Under Indian tax law, any capital gains arising from the transfer of immovable assets situated in India are subject to taxation. Navigating asset classification, indexation benefits, exemptions, and Tax Deduction at Source (TDS) is vital to ensure compliance and optimize your tax outflows.

Download the Imperial Money App to fulfill your long-term and short-term financial goals.

1. Understanding Immovable Property Categories

Immovable property covers land, buildings, or both. NRIs may acquire these assets through inheritance, family partition, gifts, using resident earnings in India, or utilizing foreign earnings. While tax provisions apply uniformly across these acquisition modes, classification matters for specific calculations:

  • Land Classification: Agricultural vs. Non-agricultural land.
  • Building Classification: Residential vs. Commercial buildings.

2. Long-Term vs. Short-Term Capital Assets

Assets are categorized based on their holding period from the date of allotment:

  • Long-Term Capital Asset: If held for more than 24 months. For inherited or gifted assets, the holding period of the previous owner is included in this calculation.
  • Short-Term Capital Asset: If held for 24 months or less.

3.Calculating Capital Gains: Cost, Improvements, and Indexation

Capital gain is determined by subtracting the acquisition cost, cost of improvement, and transfer expenses from the sale consideration. 

  • Sale Consideration: The actual amount received or the stamp duty guideline value fixed by the government, whichever is higher.
  • Cost of Acquisition: Purchase price, stamp duty, and buying commissions. For properties acquired before April 1, 2001 (or by previous owners before that date), the actual cost can be replaced by the guideline value as of April 1, 2001.
  • Cost of Improvement: Capital expenses incurred to improve asset quality (e.g., boundary walls, land leveling) on or after April 1, 2001. Proper supporting documentation and bills must be maintained.
  • Indexation Benefit: For long-term capital assets, the Cost Inflation Index (CII) is applied to adjust acquisition and improvement costs for inflation using the formula:
    Indexed Cost = Cost / Index of acquisition year * Index of sale year`.

4. Exemptions from Capital Gains (Sections 54, 54EC, and 54F)

Taxpayers can avoid or minimize capital gain taxes by reinvesting the net sale proceeds or capital gains into specified assets (such as residential houses or notified bonds) within prescribed time limits. Non-compliance with conditions at a later stage leads to the withdrawal of exemptions and immediate tax liability.

5. Tax Deduction at Source (TDS) Rules

Under Section 195 of the Income-tax Act, the buyer of an immovable property from an NRI is mandated to deduct TDS before making payments. 

  • The TDS rate is typically determined based on the calculated tax on capital gains. 
  • Both seller and buyer can approach the jurisdictional Assessing Officer (AO) via an application with supporting documents (sale agreement, PAN cards, purchase proofs, and capital gain calculations) to obtain a lower TDS certificate. 
  • If no application is made to the AO, TDS must be deducted on the total consideration amount.

6. Capital Gain Tax Rates

  • Long-Term Capital Gains (LTCG): Taxed at a flat rate of 20% without basic exemption limit benefits for NRIs, subject to potential DTAA benefits.
  • Short-Term Capital Gains (STCG): Treated as regular income and taxed according to applicable slab rates

7. Filing Return of Income and DTAA Relief

NRIs must file detailed returns for Indian-earned income, though those with only long-term capital gains where proper TDS has been deducted are exempt from filing. Under Double Taxation Avoidance Agreements (DTAA), taxpayers can choose the more beneficial tax rate between the Income-tax Act and the applicable DTAA by providing a valid Tax Residency Certificate (TRC).

8. Repatriation of Funds

NRIs can repatriate up to USD 1 million per financial year from NRO balances or asset sale proceeds, backed by a chartered accountant’s certificate. Authorized Dealers (ADs) can permit repatriation of property sale proceeds even if held for less than 10 years, provided the cumulative holding period in India and retention within the NRO account equals at least 10 years.

Conclusion

Managing property transactions as an NRI requires careful tax planning, documentation, and adherence to legal frameworks. Consult with financial professionals to optimize your tax liabilities and protect your hard-earned wealth. 

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
Yes!!! The Youth Are Ready For Investment

India boasts one of the youngest populations in the world, with a rapidly growing demographic under the age of 40. Alongside national development, people across all age groups are becoming increasingly aware of the financial world. Today’s youth are remarkably curious about economic mechanisms and are taking a keen interest in wealth creation. As living standards rise, young earners are actively planning to save and grow a significant portion of their income.

1. The Changing Financial Mindset of Young Adults

Unlike pre-millennial generations, modern youth look far beyond traditional stagnant savings. According to a survey by Innovative Research Services (India) for Tata Capital (as reported by The Economic Times), 39% of young adults aged 18 to 25 save about a quarter of their income. They channel these savings into bank deposits, mutual funds, and market investments. However, jumping into investments without proper planning can lead to avoidable financial losses, making professional guidance essential from day one.

2. Why Mutual Funds and SIPs Are Ideal for Beginners

For young earners starting their wealth-building journey, mutual funds and Systematic Investment Plans (SIPs) offer unmatched advantages:

  • Superior Returns: Mutual funds historically deliver higher annualized returns of 10% to 15%, comfortably outperforming traditional bank deposits and fixed deposits (6% to 7%).
  • Instant Diversification: Instead of buying individual stocks, a single mutual fund gives you exposure to a professionally managed, diversified basket of securities and bonds.
  • Financial Discipline: SIPs allow you to invest small, fixed, and affordable amounts at regular intervals, saving you from the stress of trying to time the market.

3.How to Start Your SIP Journey

Before committing funds, smart investors utilize online tools like SIP calculators and SIP lump sum calculators to project potential returns based on regular contributions, expected interest rates, and investment duration. Because selecting the right fund can be overwhelming for beginners, consulting a certified mutual fund planner ensures your portfolio aligns with your long-term goals.

4. Why Youth Should Prioritize SIPs Now

Young adults possess two massive advantages time and flexibility. Because they are at the beginning of their careers with smaller initial capital pools, SIPs provide the flexibility to start small while instilling lifelong financial discipline and compounding momentum from an early age.

Conclusion

The youth of India are stepping up and proving that they are ready to take control of their financial destinies. By starting early, harnessing the power of SIPs, and seeking expert guidance from Imperial Money, young earners can build a rock-solid foundation for lifelong wealth and freedom.

Note: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.
Why Liquid Funds Are the Smart Alternative to Short-Term Fixed Deposits

Liquid Funds vs Fixed Deposits: smart alternative banner Smart Alternative to Short-Term Fixed Deposits banner with liquidity and Imperial Money logo

Liquid funds vs fixed deposit choices often come down to one core dilemma: flexibility versus guarantees. Liquid funds are a smart alternative to short-term fixed deposits because they typically offer easier access to your money, little to no penalty for withdrawing early, and returns that are broadly comparable to short-term FD rates—without locking your cash away. For anyone utilizing liquid funds for short-term investment or parking a lump sum for a few months, that flexibility often matters more than the interest rate itself.

If you’ve ever booked a short-term FD and then needed the money back early—only to watch the bank quietly deduct a penalty from your interest—you already know the problem liquid funds are built to solve.

1. What Are Liquid Funds?

A liquid fund is an open-ended debt mutual fund that invests in short-term money market instruments—things like treasury bills, commercial paper, and certificates of deposit—with maturities of up to 91 days.

Because the underlying instruments mature so quickly, liquid funds are less sensitive to interest rate swings than other debt funds, and the fund can typically process your redemption requests fast—usually within one business day. They’re regulated by SEBI, and every liquid fund scheme comes with a scheme information document that spells out exactly what it invests in.

2. Liquid Funds vs Fixed Deposits: What’s the Real Difference?

On the surface, FDs and liquid funds look similar—you park money for a while, and it grows. But how each one behaves when you actually need your money early is where they part ways.

Liquidity and Withdrawal Speed

A bank FD usually needs a visit to the branch or a request through net banking, and the funds may take a day or two to reflect. Liquid funds, on the other hand, typically process redemptions within one business day, and many fund houses offer instant redemption for smaller amounts credited within minutes.

Premature Withdrawal — Penalty vs (Almost) No Penalty

Most people do not anticipate this phase. Most banks charge a penalty—typically 0.5% to 1%—on your FD interest if you break it before maturity. So if your FD was earning 7% and you exit early, you might only end up earning 6% or 6.5%, and sometimes even less depending on the bank’s policy.

Liquid funds work differently. SEBI mandates a graded exit load only for redemptions within the first 7 calendar days of investing—and this fee reduces day by day. After 7 days, there’s typically no exit load at all. So if you’re parking money for a few weeks or months (which is the whole point of a liquid fund), you’re very unlikely to pay any penalty for withdrawing early.

Liquid Funds Taxation — FD Interest vs Liquid Fund Gains

When looking closely at liquid funds taxation, it’s worth being precise because a lot of content online is outdated on this point:

  • Fixed Deposits: FD interest is added to your total income and taxed at your income tax slab rate every year, whether you withdraw it or not, and banks deduct TDS if your annual interest crosses the prescribed threshold.
  • Liquid Funds: Since the tax law changes effective from April 2023, liquid funds taxation rules dictate that gains are also taxed at your slab rate on redemption; the earlier benefit of long-term capital gains with indexation no longer applies to debt mutual funds, including liquid funds.

From a pure tax-rate perspective, liquid funds and FDs are now taxed quite similarly. The real difference is in when the tax applies (only on redemption, not accrued annually) and that there’s generally no TDS deducted on your liquid fund gains the way there is on FD interest above the threshold—useful if you’d rather not have tax deducted upfront and adjust it yourself while filing returns. As always, please check the current rules with your tax before making a decision.

3.Why Liquid Funds for Short-Term Investment Are a Smart Alternative

Put together, here’s what actually makes liquid funds a compelling short-term option:

  • Little to no exit penalty after the first week—unlike FDs, which typically charge one at any point before maturity.
  • Fast access to your money—often within a day, sometimes within minutes.
  •  No fixed lock-in—you decide how long to stay invested, from a few days to several months.
  • Liquid fund returns vs FD interest rate comparisons show that while yields are broadly in line with short-term FD rates, liquid fund returns are market-linked and not guaranteed the way FD returns are.

That said, liquid funds are not a replacement for an FD in every situation. If your goal is a completely fixed, guaranteed return with zero market exposure, an FD (within the ₹5 lakh DICGC insured limit per bank) still has a role to play.

4. What to Know Before You Switch

Liquid funds are considered one of the lower-risk categories of mutual funds, but “lower risk” isn’t the same as “risk-free.” A few things worth knowing:

  • Returns are not guaranteed: Unlike an FD, where the rate is locked in at the time of booking, liquid fund returns move with prevailing money market conditions.
  • Credit risk exists: Liquid funds invest in instruments issued by banks, corporates, and the government—a downgrade or default in one of these can affect the fund’s NAV, though most liquid funds stick to high (AAA-rated) quality instruments.
  • NAV can dip slightly: It doesn’t happen often, but liquid funds aren’t entirely immune to short-term market stress.

None of this makes liquid funds unsuitable for short-term parking—it just means you shouldn’t treat them as identical to a bank deposit. Please read the scheme documents and, ideally, consult a financial advisor before investing.

5. A Quick Example

Say you’ve received a bonus of ₹3 lakh and know you’ll need it in about 4 months for a planned expense.
If you put it in a 6-month FD and need to break it after 4 months, the bank may apply a premature withdrawal penalty on the interest earned—so instead of earning the full contracted rate, you’d typically end up earning something lower.
If you’d instead parked it in a liquid fund, you could redeem after 4 months with no meaningful exit load (since it’s well past the 7-day window), and your actual returns would broadly track what the fund earned over that period—without a penalty eating into it simply because your timeline shifted.

This is illustrative only—actual outcomes depend on the specific bank, fund, and prevailing rates at the time.

6.How to Start Investing in a Liquid Fund

  • Complete your KYC: If you’ve invested in mutual funds before, this is likely already done.
  • Choose a liquid fund: Look at the portfolio’s credit quality, expense ratio, and fund size before picking one.
  • SIP: For short-term parking, a lumpsum investment is more common, but there’s no restriction either way.
  • Invest through a registered platform or distributor: Keep an eye on the exit load structure and redemption timelines of the specific scheme.
  • Track and redeem when needed: Most platforms show your investment value in real time.

Frequently Asked Questions

  • Are liquid funds better than fixed deposits?
    It depends on what you value more—a liquid fund typically offers faster access and little to no early-withdrawal penalty, while an FD offers a fixed, guaranteed return. For short-term parking where your exit date isn’t fixed, are liquid funds better than fixed deposits? Often yes, because they provide a much more flexible choice.

  • Can I lose money in a liquid fund?
    It’s uncommon, but liquid funds are market-linked and not risk-free the way an FD is. Short-term dips in NAV are rare but possible.
  • How is liquid fund taxation different from an FD?  
    Since April 2023, gains from liquid funds are taxed at your income slab rate on redemption, similar to FD interest—the key practical difference is timing (taxed on redemption vs. annually accrued) and TDS treatment, not the tax rate itself.
  • Is there really no exit load on liquid funds?  There’s typically a small, graded exit load only if you redeem within the first 7 calendar days. Beyond that, most liquid funds don’t charge one.

Not Sure Which Option Fits Your Situation?

Every short-term goal is a little different—how soon you might need the money, how much certainty you want, and your tax situation all play a role. When weighing liquid funds vs fixed deposit strategies for your cash surplus, if you’d like help figuring out where to park your short-term surplus, it’s worth a quick conversation with our experts at Imperial Money.